

The war between the US and Iran seems not to have an end in sight. The war between Russia and Ukraine has gone on since 2014, and although the parties appear fatigued, that financing difficulties are apparent on both sides, and that infrastructure in both countries is increasingly dysfunctional, there is no end in sight either. Do they have anything in common? Fossil fuels, amongst many things.
More broadly, since the great financial crisis, and then since COVID, nothing is the same anymore. Sovereign debt levels have gone up to their limit, bringing up risk of financial or monetary instability. Climate impacts have become more palpable and destructive. Economic resilience appears very low.
We saw the full invasion of Ukraine by Russia, then a severe disruption of oil and gas markets. Then the first inflation crisis in decades as costs were pushed up, and businesses took the opportunity to set higher prices, and in some cases even increase profits. Oil companies saw a record large conflict dividend. Higher costs spread across economies and caused a cost of living crisis. We then saw the destruction of Gaza, after which Israel attacked Iran with US support. Iran blocked the Strait of Hormuz, under intermittent fire exchange with the US. The price of oil and especially gas followed a roller coaster. Israel issued exploration licenses for natural gas in Palestinian waters. Offshore oil and gas development restarted in Venezuela, in the context of the Strait of Hormuz blockade, after the US army captured its president. These are but just a few of the events of the last six years.
Business as usual? Is this just observer bias, leading us to wrongly think that we’ve entered a period of instability, because we remember more vividly the last six years than what happened before? There are a few differences before and after COVID however. The fact that it is more difficult to fly from the UK to East Asia is telling. There is only one, narrow passage, over Central Asia, Azerbaijan and Turkey, between the conflict zones.
The mid-transition hypothesis
Back in 2018 and 2021, our research team made a fateful prediction that fossil fuel demand would peak, and as a result, conflict could arise ahead of 2030 as a result of pressures in oil and gas markets. Not that we’d run out of the fossil resources, but the opposite. That we’d have excess amounts and that the scarcity of demand would create incentives for oil and gas conflict or war. I also refer to this in my book with Hector Pollitt, ‘Rethinking Climate Policy’.
In 2023, in a working paper for the International Monetary Fund, Etienne Espagne, William Oman, I and co-authors suggested that we’ve entered what’s called the ‘mid-transition’ era, a period of time during which arise many stresses and overlapping drivers of volatility globally, including climate change impacts, stranded assets, rapid technological change, all potentially causing problems in macro-financial balances of countries (Figure 1A). Some of the problems are mediated across borders, for example, where oil importers invest in electric cars to reduce their import bill, causing economic damage to oil producers. Or where technology importer countries generate economic activity in green technology importers because of their choices of climate policies (Figure 1B).
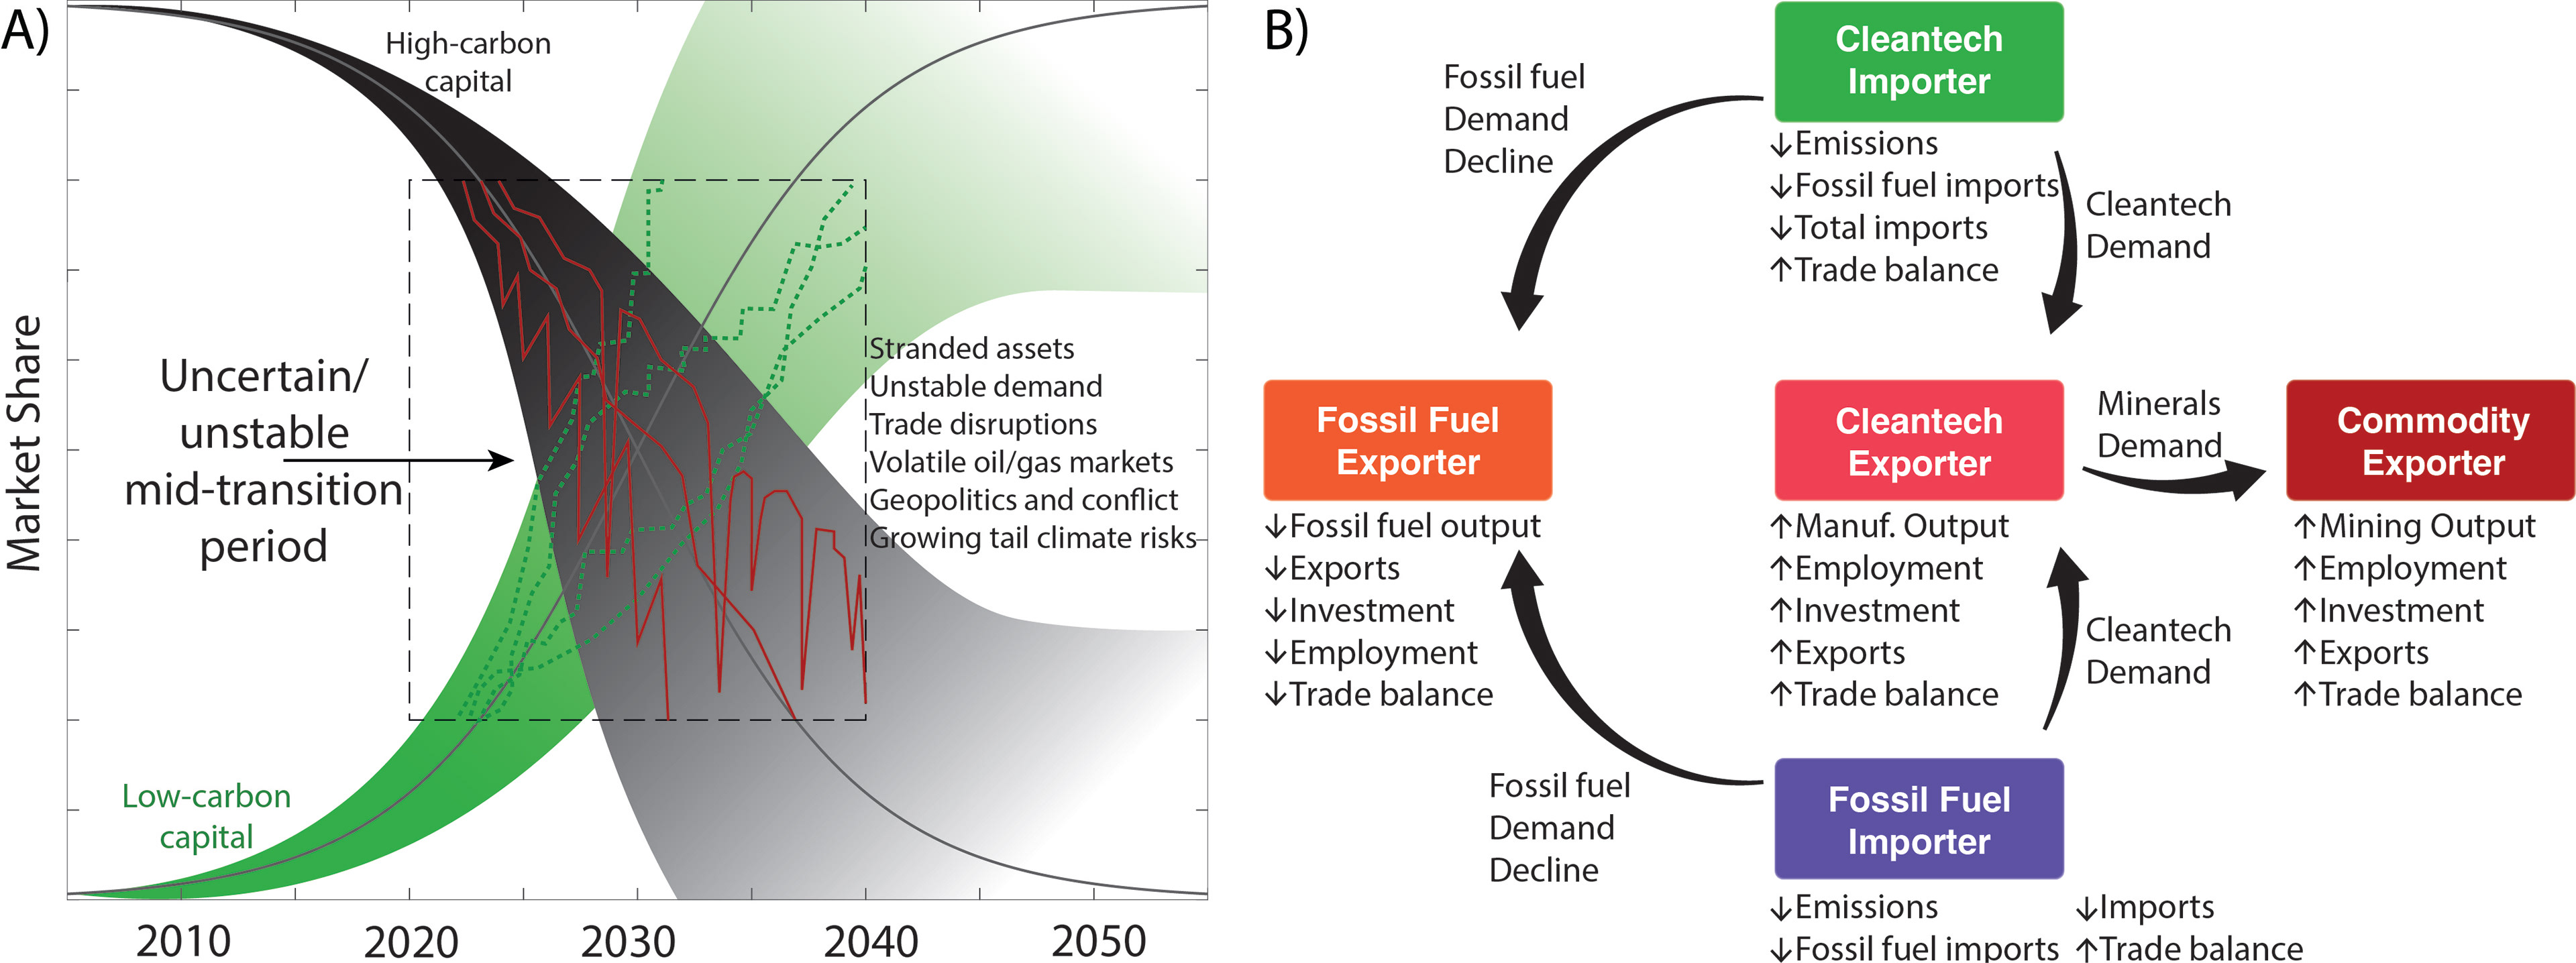
Predictions are hard to validate. But it is quite possible that our predictions on fossil fuels become at least partially realised this year or the next, looking at demand. For the broader mid-transition hypothesis, it’s much harder to measure, but geopolitical risk indices are consistently higher and on the rise since around 2020. This doesn’t mean we are necessarily correct, therefore let me explain below why we believe this is right.
Structural transformation as driver of global macro-financial volatility
The first order driver of global volatility is the notion that a world without fossil fuel consumption would involve a completely different global geography of economic and military power. The map of power is changing now because low-carbon technologies affect global fossil demand, mainly in China, Korea, Japan and Europe, affecting the economic power of fossil producers. These centres of demand have for the longest time had the incentive to reduce the drain that fossil imports cause to their economies via the trade balance. Climate action for them has a double dividend in addressing both climate and the balance of trade. Imports of fossil fuels are typically the largest on trade accounts of non-producer countries. Removing that leaves a lot of money (in foreign currency) to spend on other essentials such as medical supplies. A quick analysis of energy policies in those countries confirms their focus on limiting energy imports (see for instance the 2014 book Planetary Economics by Michael Grubb).
Conversely, this is foreign currency that the fossil producers stop receiving (Figure 2). This can in turn push them into liquidity problems, for instance difficulties in servicing external sovereign debt.
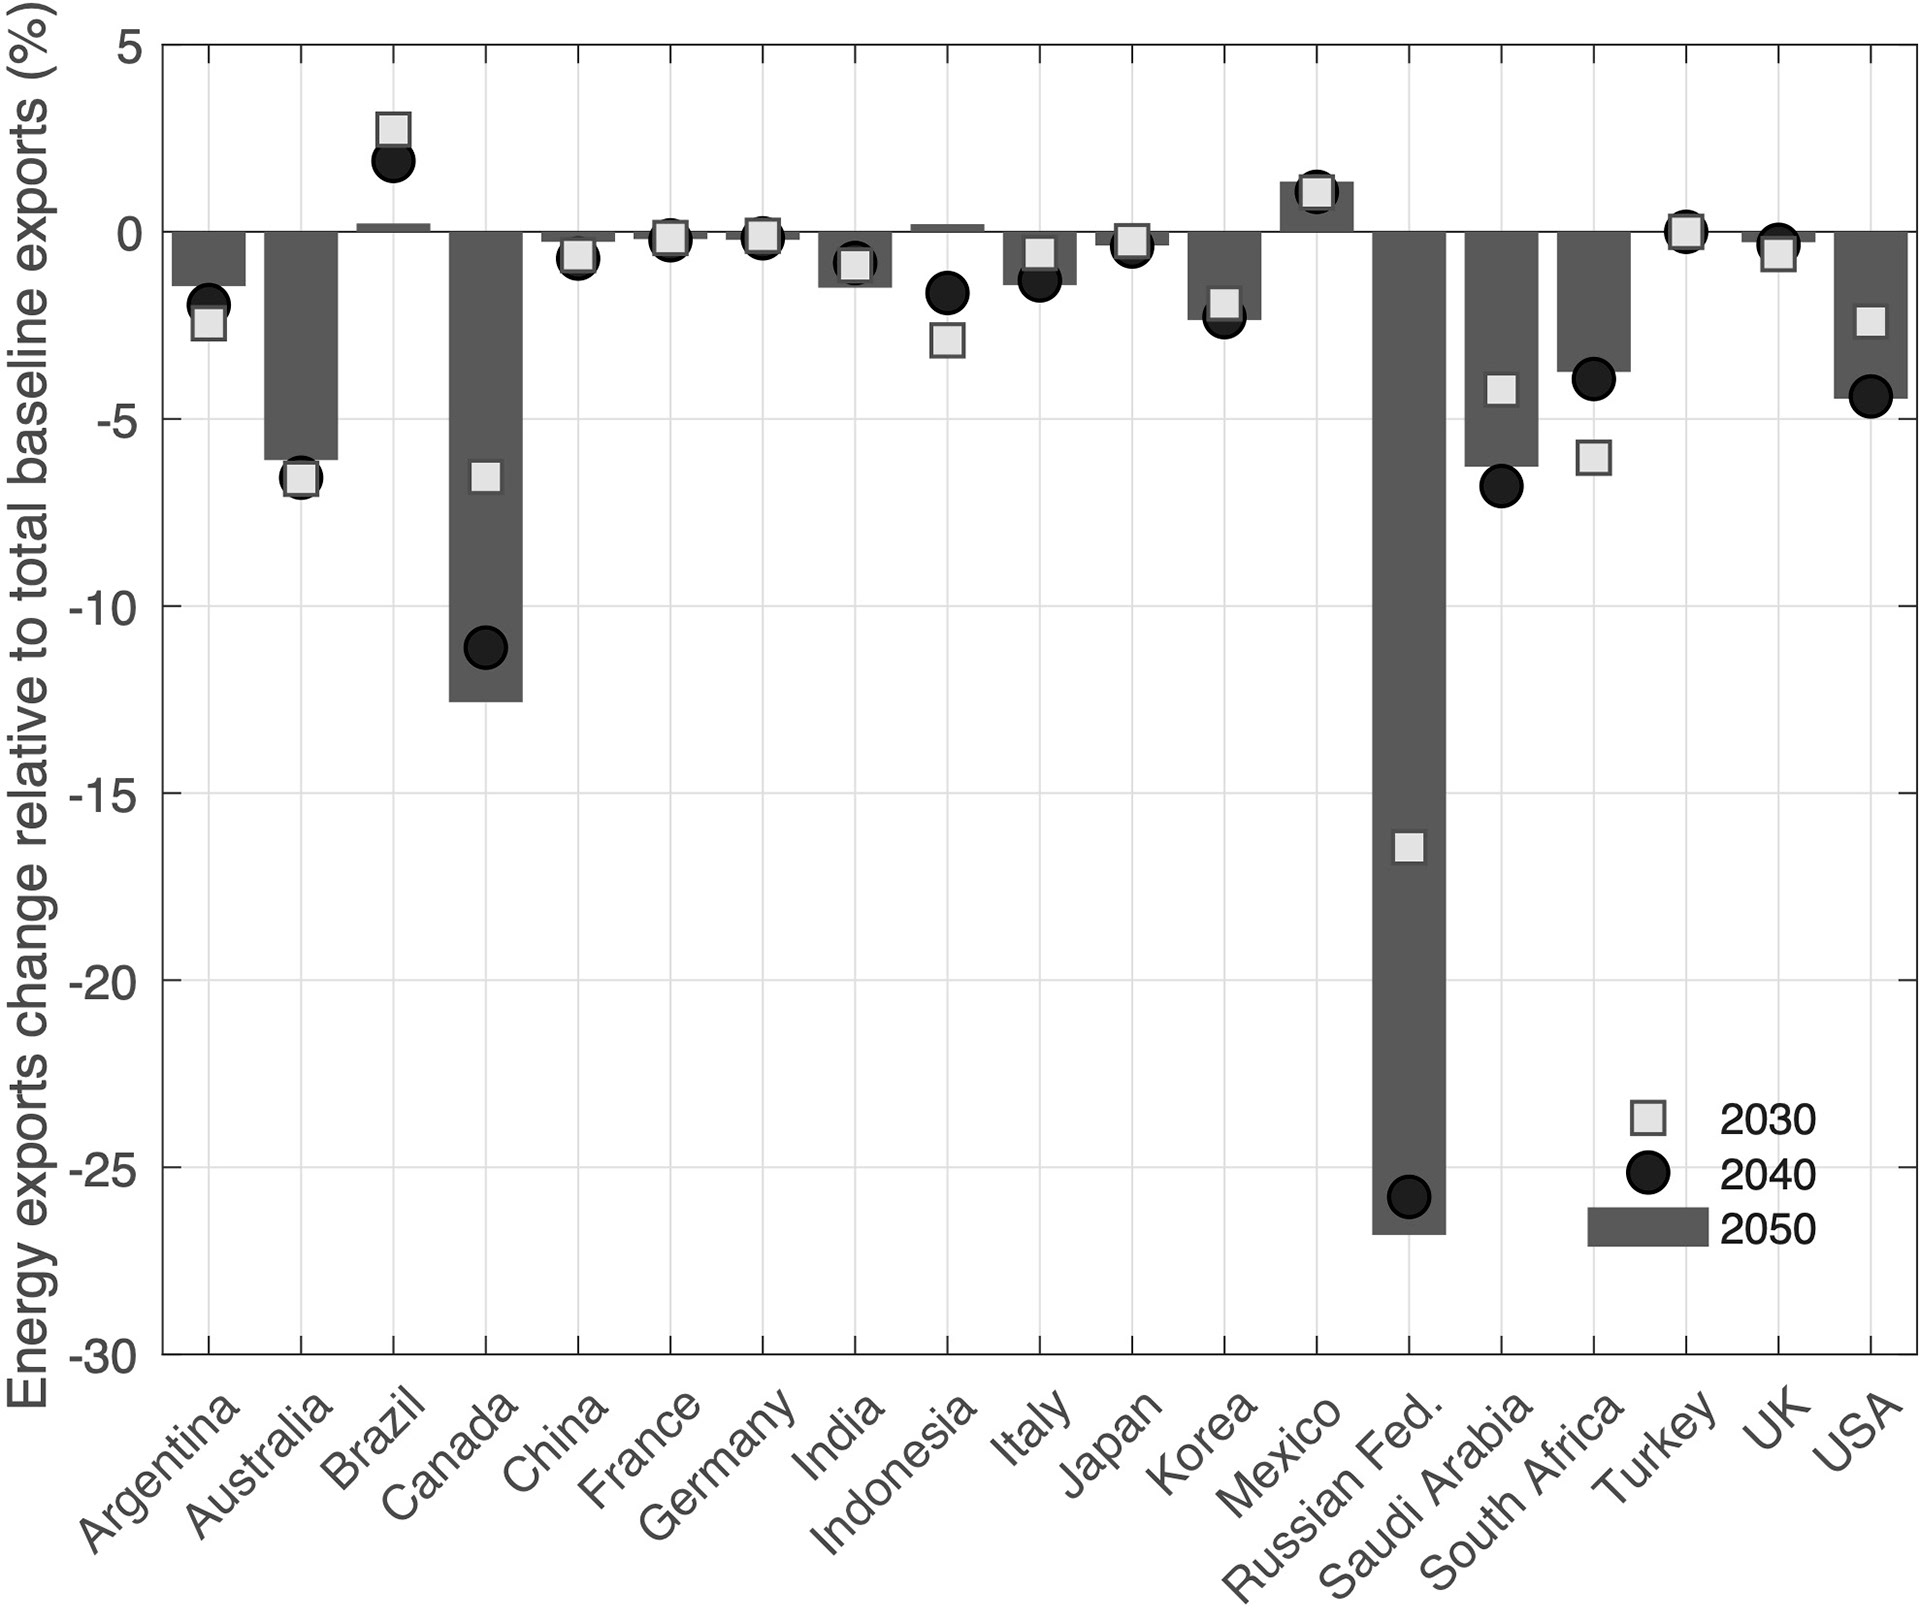
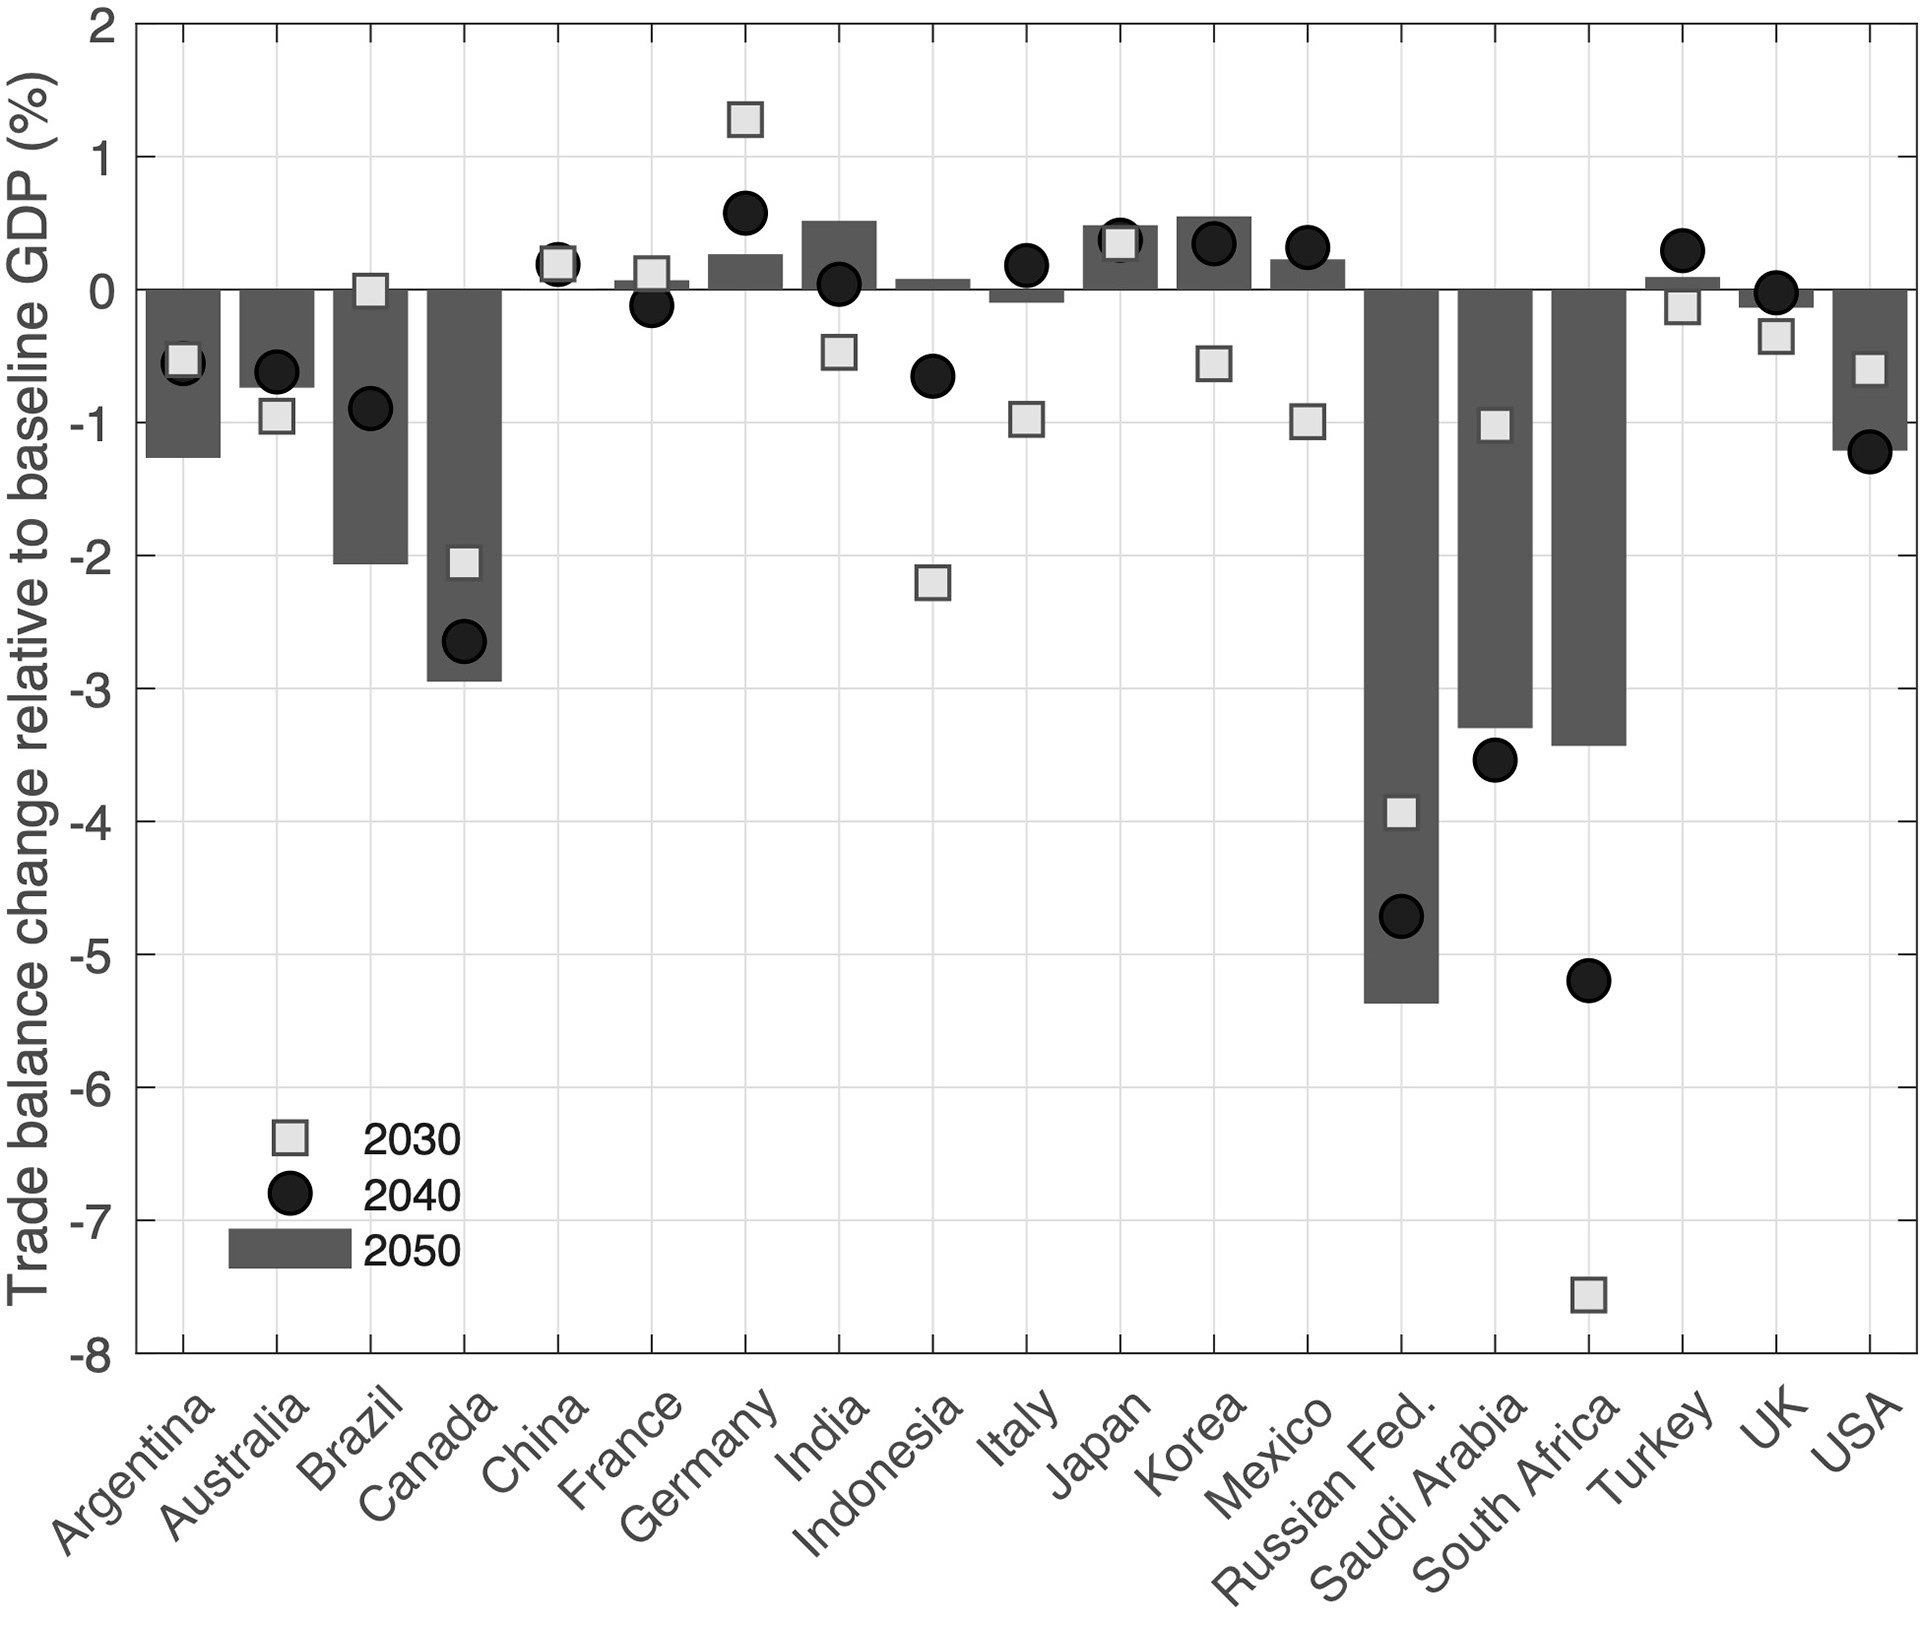
China, one of the largest importers of oil and gas worldwide, is peaking its emissions more or less now, while it consumes 15% of global oil and 10% of gas (Europe consumes 14% and 15% respectively, and following a similar path). The implied lack of demand growth, from 30% of global users, is significant for fossil markets. Not to say that demand is in free fall, it continues to be strong in some parts of the world, but it is flat in at least China and Europe.
Along with my research network, we thought for some time that this leads to perpetually low fossil prices and insolvency of fossil companies due to stranded fossil fuel assets. But we may have been partially wrong. Instead, declining demand might lead to a cyclical alternation between glut and scarcity, for two reasons. First, because competing fossil producers don’t have a mechanism to coordinate who, amongst them, stops producing. Second, investor behaviour alternates between causing future excess capacity when prices are high, during short-lived euphoria, and causing future scarcity when investment drops due to pessimistic expectations. We already see this of course, but the alternation could accelerate under pressure, and possibly what we are seeing roughly since COVID.
A key deciding factor for determining who loses the fossil production musical chair is the cost of production of course, and we’re well aware that Saudi oil is substantially less costly to get out of the ground than Arctic oil or tar sands. In principle, if we believed the economic theory of comparative advantage, the less competitive producers should give up first. We made detailed calculations around this in 2021, and found that (1) oil and gas importers such as Europe and East Asia can unilaterally gradually stop consuming, with some economic advantages from green job creation, and there would be little oil and gas producers could do to stop them. In response, low-cost oil and gas producers such as Middle-Eastern countries could unilaterally flood markets if they wanted, by increasing production to grab market share, and pushing higher cost producers out (US, Russia, Canada), and there’d be little these countries could do to stop them. This way, low-cost producers pass on the economic damage from lost output to the high-cost producers. The resulting effects on country GDP of high-cost producers from those market power dynamics are frightful. Hence we can understand that those countries may not be inclined to allow such scenarios to materialise. And indeed, this is not quite what we have seen since 2021.
Of course, fossil producers can invest some efforts into slowing down the transition away from fossil fuels, especially the US. We also see this, with Trump revoking offshore wind project licenses, and creating more incentives for oil and gas development. Such actions can influence domestic uptake of low-carbon technologies in fossil producer countries, but may have very limited impact on technology developments in East Asia and Europe.
Conflict and war emerges as a possible response mechanism
One obvious effective way to keep producing, if you’re amongst those in trouble, is to push other producers out of fossil markets using ‘other methods’ than market mechanisms. Now is the time when oil producers have money and capacity, and therefore, when they can stock up on weapons and use them. Hence it would be plausible to see conflict. And that’s potentially what we see. This is not new, oil-related conflict has been part of the supply-demand equation since the start of the 20th century.
However, as we should expect, it’s much more complicated than that. It is quite clear in the conflict between US allies and Iran that economic structure matters. One might have thought that Saudi Arabia had the capacity to stay on top of oil markets given its very large market power. But it turns out that Iran has much more economic stamina, and it didn’t take long during the current conflict for Saudi Arabia and the UAE to become very quiet. Part of it is, they are largely un-diversified economies wholly dependent on oil, and although they have vast stockpiles of weapons, they have much smaller armies. And with the Strait of Hormuz blocked, they are in macro-financial trouble.
Iran, in contrast, is a diversified economy that hasn’t deindustrialised like Western countries, largely because it hasn’t really joined in free trade. It has maintained strategic industries such as steel, and is a large food producer, able to live cut off from trade. Not being able to join free trade has been a drag on growth, but all of a sudden, economic resilience is their most valuable asset.
The emergent ability of Iran to play a long game and block the Strait of Hormuz, and the inability of the US to unblock it, is a turning point in global geopolitics. And there is something much deeper within this problem of the Strait of Hormuz than just controlling who gets through. Iran has been letting through ships to or from friendly but not US-aligned nations, including China. In a remarkable turn of history, a situation of oil and gas glut was turned into one of scarcity. Blocking the exit of Saudi and UAE oil to the West has left a gap in the market that other producers have barely been able to plug, at a time when we ought to have too much oil. Strategic reserves even in the US are at a historical low, and prices remain high, risking a return of inflation. Iran has discovered an inflation red button that it can press.
There is then Russia and the Ukraine war. Russia gets much of its economic power via oil and gas exports (Figure 2), hence it contemplates a bleak future as China reduces its demand for oil for transportation, and Europe attempts to wean its industry and buildings heating off gas. What’s the connection with the war in Ukraine? It’s ambiguous, but gas network geopolitics and EU economic integration played a defining role, where Ukraine sought independence from Russia. Russian throttling on and off gas flows as a tool for pressure on Europe have been a defining feature of pre- and post-invasion dynamics. Gas is a key source of power for Russia.
And lastly, we see an increasing fragmentation of global energy markets, where many shipments occur outside of formal Western markets. This started with the war in Ukraine and sanctions from Europe and the US on Russian oil, shutting Russia out of Western shipping insurance markets. This led to the emergence of a ‘ghost’ Russian oil tanker fleet, ships that are difficult to identify, operating outside of formal markets to get around sanctions.
Navigating fossil-related macro-financial risk
So the conclusion is that our predictions were part correct, part wrong. We were right to say that the ongoing decarbonisation could cause conflict. We were potentially wrong thinking that fossil prices would become low and cause stranded oil and gas resources via market mechanisms. We were probably right in anticipating a volatile ‘mid-transition’. But a critical emergent finding is as follows.
That oil traded in US dollars is trapped in the Persian Gulf is significant. Oil, which the demand shows signs of peaking, and gas, which may not continue to grow indefinitely, are increasingly traded in other currencies than the dollar, in yuan and rouble. The significance of this is that it affects the balance of the petrodollar system. Petrodollars were the dollars traditionally paid for importing oil by most countries, something that conveyed a vast international flow of dollars relative to other uses. That flow would accumulate into stocks in oil-producing countries, notably the Saudi sovereign wealth fund. Those dollars would find their way back to the US through investment flows, where for example, Saudis and Russians would buy real estate in the US in order to ‘park their cash’. This great inflow on the current account would enable the US to have a vast trade deficit. Just as all roads lead to Rome, all petrodollars ultimately lead to the US and its economic power. Oil is of course not the only market in which this occurs. But an end to buying oil in dollars internationally means an immediate reduction in the ability of the US to sustain its trade deficit, and could lead to a devaluation of the dollar. It affects US economic power and its ability to maintain a US-aligned world order.
In a scenario of fossil peak demand, all fossil fuel producers may find themselves having to navigate macro-financial instability, between debt and monetary crises and financial crises.


